
 Article
 Brochure
 Executive Resource
 Insight Hub
 Ext. Publication
 Video
What Is a Step-Up in Basis? How Inherited Property Can Receive a Tax Advantage
Accounting Advisory Services
Never miss a thing.
Sign up to receive our Tax News Brief newsletter.
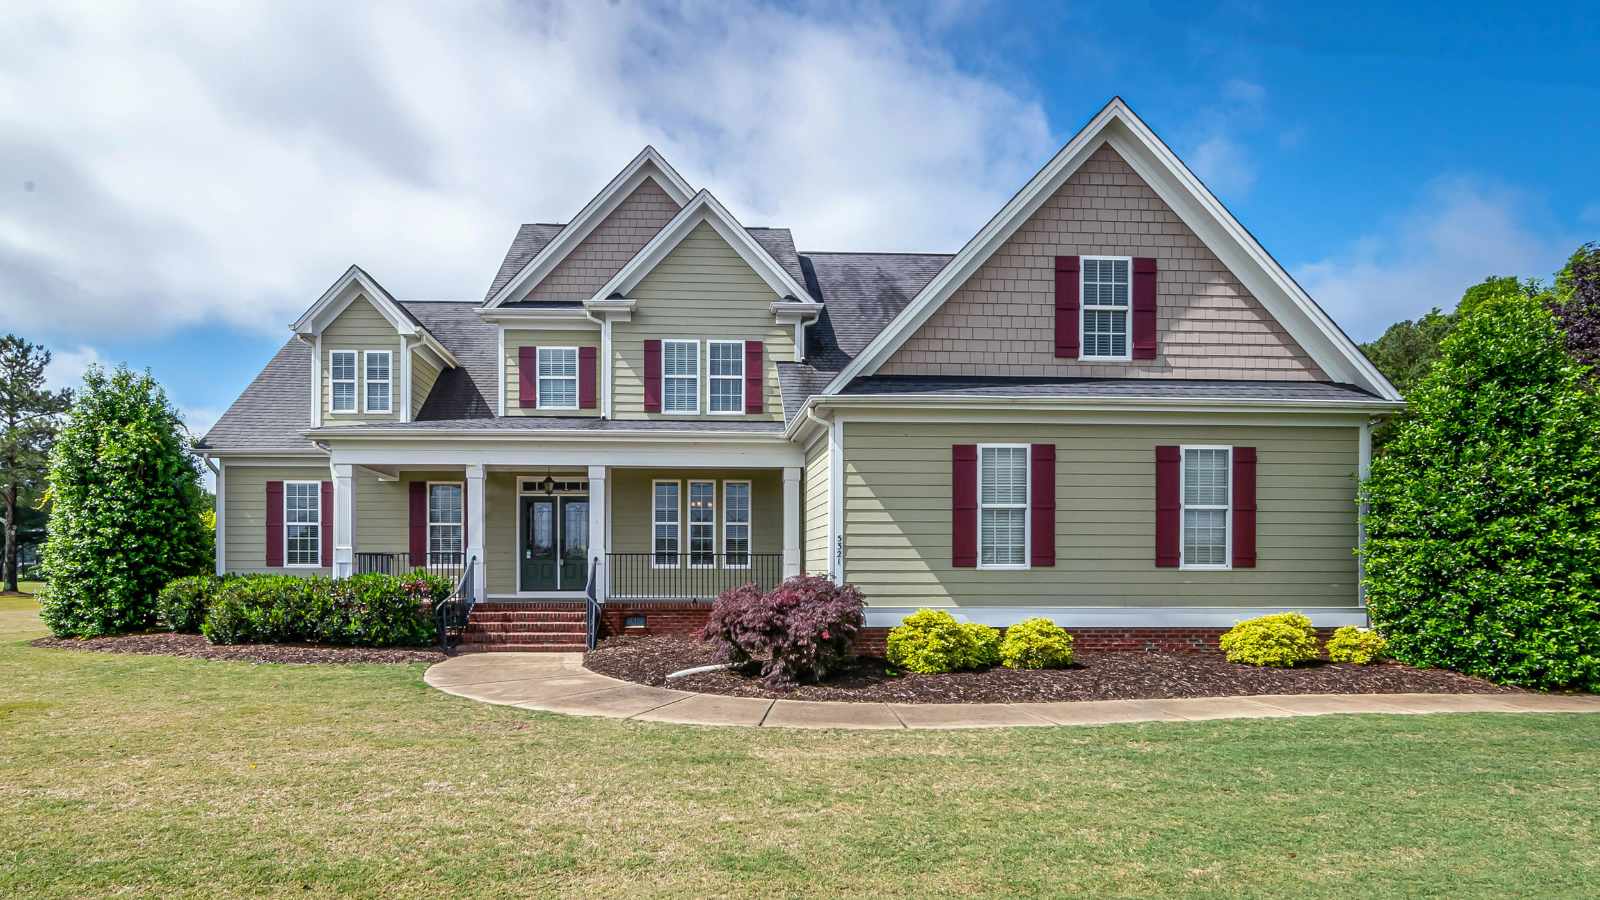
Many people worry about inheriting a house because they assume they will owe huge taxes when they eventually sell it. Fortunately, that is often not the case.
One of the tax benefits available to heirs is called a “step-up in basis.” While the name sounds technical, the concept is straightforward, and it can significantly reduce capital gains taxes when inherited assets are sold. This basis adjustment can preserve more of an inherited asset’s value and help avoid unexpected tax consequences.
For families inheriting a home, rental property, investment account or other appreciated asset, understanding how step-up in basis rules apply can help inform tax and financial planning decisions.
What Is Basis and Why It Matters
In simple terms, a taxpayer’s tax basis is generally the amount paid for an asset, adjusted over time for certain additions, improvements, depreciation or other tax-related factors. For example, if an individual purchases a home for $300,000, the initial tax basis is typically $300,000. If the individual later sells the property for $800,000, there may be a gain of approximately $500,000 before considering any additional adjustments, deductions or exclusions. Because capital gains taxes are generally based on the difference between the sale price and adjusted basis, a larger gain can result in a larger potential tax liability.
How a step-up in basis works after death
The tax treatment of inherited assets often differs from that of assets acquired during a person’s lifetime. When a person dies, many assets that pass to heirs receive a new tax basis based on the asset’s fair market value at the date of death. This adjustment is commonly known as a “step-up in basis.” Instead of inheriting the original owner’s decades-old purchase price, heirs generally receive tax basis equal to the property’s value at death.
A real-world example of the tax savings
Suppose a mother purchased a home in 1985 for $150,000, and by the time of her death, the property had appreciated to $1.2 million. Without a step-up in basis, if the home were sold for $1.2 million, the taxable gain would be $1,050,000 ($1.2 million sale price minus the original $150,000 basis). However, with a step-up in basis, the property’s basis is adjusted to its fair market value at the date of death or $1.2 million. As a result, if the heirs sell the home for $1.2 million, there would be no taxable capital gain.
While actual calculations can be more complex, this example demonstrates why a step-up in basis can provide significant tax savings for heirs.
Does Every Asset Receive a Step-Up?
A step-up in basis is not limited to inherited homes and can also apply to many other inherited property types and investments. Common examples include residential homes, rental properties, commercial real estate, stocks, mutual funds and certain business interests. In general, these assets may receive a basis adjustment to their fair market value as of the owner’s date of death, potentially reducing or eliminating capital gains taxes when they are later sold.
However, some assets follow different tax rules. Retirement accounts such as traditional IRAs, 401(k)s and similar tax-deferred accounts generally do not receive the same step-up treatment. Instead, beneficiaries often face separate distribution and income tax rules. The distinction is important because two inherited assets may have very different tax consequences, even when they are received from the same estate.
When Selling or Keeping Inherited Property, Basis Still Matters
Selling shortly after inheritance
In many situations, selling shortly after inheritance results in little or no taxable gain because the property’s tax basis has already been adjusted to its fair market value at the date of death. However, property values do not remain static. If the property increases in value after the date of death and before the sale, some gain may still be taxable. Likewise, if the property decreases in value, other tax considerations may arise.
Keeping inherited property long term
Many heirs choose not to sell inherited property immediately. Instead, they may decide to move into the home as their primary residence, rent it to tenants to generate income, hold it as a long-term investment expecting future appreciation or transfer ownership interests among family members as part of their estate or financial planning goals.
The stepped-up basis generally remains important because it may affect future capital gains calculations when the property is eventually sold. Understanding the property’s adjusted basis can help inform future ownership, investment and sale decisions.
Common Myths About Inherited Property and Taxes
A common misconception is that heirs automatically inherit their parents’ original purchase price, or tax basis, on a property. In many cases, however, heirs receive a basis determined under federal tax rules rather than the basis held by the original owner.
Another misconception is that inheriting property automatically creates an immediate tax bill. Generally, simply receiving inherited property does not trigger income taxes. Instead, any future tax consequences often depend on what the heir chooses to do with the property, such as selling, renting or transferring it.
Property taxes and tax basis are also commonly confused even though they serve different purposes. Property taxes are based on a property’s market value and the county’s assessment rules, which determine the amount of annual real estate taxes owed. Tax basis is used to calculate potential capital gains or losses for federal and state income tax purposes when a property is sold. Confusing these concepts can lead to costly planning mistakes and unexpected tax consequences.
Why Accurate Valuation Matters
The step-up in basis depends heavily on determining the property’s fair market value at the date of death. Unfortunately, many families fail to document this value properly. Years later, when the property is sold, they may struggle to prove their tax basis to the IRS.
Without adequate documentation, establishing the property’s adjusted basis can become more difficult and may increase the risk of disputes or questions during a tax examination. Obtaining a qualified appraisal or other reliable valuation support shortly after inheritance can help preserve important records and simplify future reporting requirements.
Trusts and Step-Up in Basis: What Families Should Know
Some families may assume that placing property into a living trust eliminates the step-up in basis. In fact, many revocable living trusts are specifically designed so that assets continue to receive basis adjustments upon death.
Trust structures can vary significantly, and the tax consequences associated with inherited property often depend on the specific circumstances involved. The type of trust, community property considerations, ownership structure and estate planning objectives can all affect how basis adjustments and other tax rules are applied. As a result, two estates with similar assets may experience very different tax outcomes.
For that reason, trust administration often involves coordination between tax and estate planning professionals to help evaluate assets appropriately and identify potential planning opportunities.
Avoiding Costly Mistakes When Selling Inherited Property
Inherited property can present a variety of tax and planning considerations. Overlooking them may lead to costly mistakes.
Common pitfalls include:
- Selling real estate before understanding the property’s tax basis
- Failing to obtain a professional valuation as of the date of death
- Assuming that inheritance automatically creates a tax liability
- Confusing property tax reassessment rules with capital gains tax rules
- Transferring inherited assets before evaluating the associated tax consequences
- Overlooking potential basis-planning opportunities available through certain trust structures.
Early planning and analysis can result in significant tax savings later.
Before selling inherited real estate, families should evaluate the tax and legal factors that may affect the transaction. This begins with establishing the property’s adjusted basis, confirming if a step-up in basis applies and documenting the fair market value as of the date of death.
Families should also assess potential capital gains exposure, reviewing any trust or estate administration issues and consider applicable state and federal tax implications. A thorough review before the sale can help identify planning opportunities and minimize the risk of avoidable tax consequences.
Weaver Can Help
Inherited property often carries important tax considerations that can affect future decisions related to ownership, disposition and long-term planning. Ownership structure, trust provisions, valuation support and the nature of the assets involved can all influence the outcome.
If you have inherited property and are unsure how step-up in basis rules may apply, Weaver can help. Our team works with heirs, trustees, executors and families to determine basis, evaluate tax implications and plan for future property transactions. Contact us.
Authored by Tadeh Papelian
©2026
