
 Article
 Brochure
 Executive Resource
 Insight Hub
 Ext. Publication
 Video
The Future of Fraud Detection: Combining AI, Analytics and Human Judgment
Forensics & Litigation Services
Forensics & Litigation Services
Never miss a thing.
Sign up to receive our insights newsletter.
When the Oakland A’s embraced advanced analytics in the early 2000s, they weren’t trying to reinvent baseball. They were trying to find things other teams were missing.
The approach made famous by the book and movie Moneyball showed how data could reveal patterns that traditional scouting might overlook. But baseball eventually learned another lesson: analytics worked best when combined with the experience and judgment of people who knew the game. The most successful teams found value in both.
Fraud detection is undergoing a similar evolution.
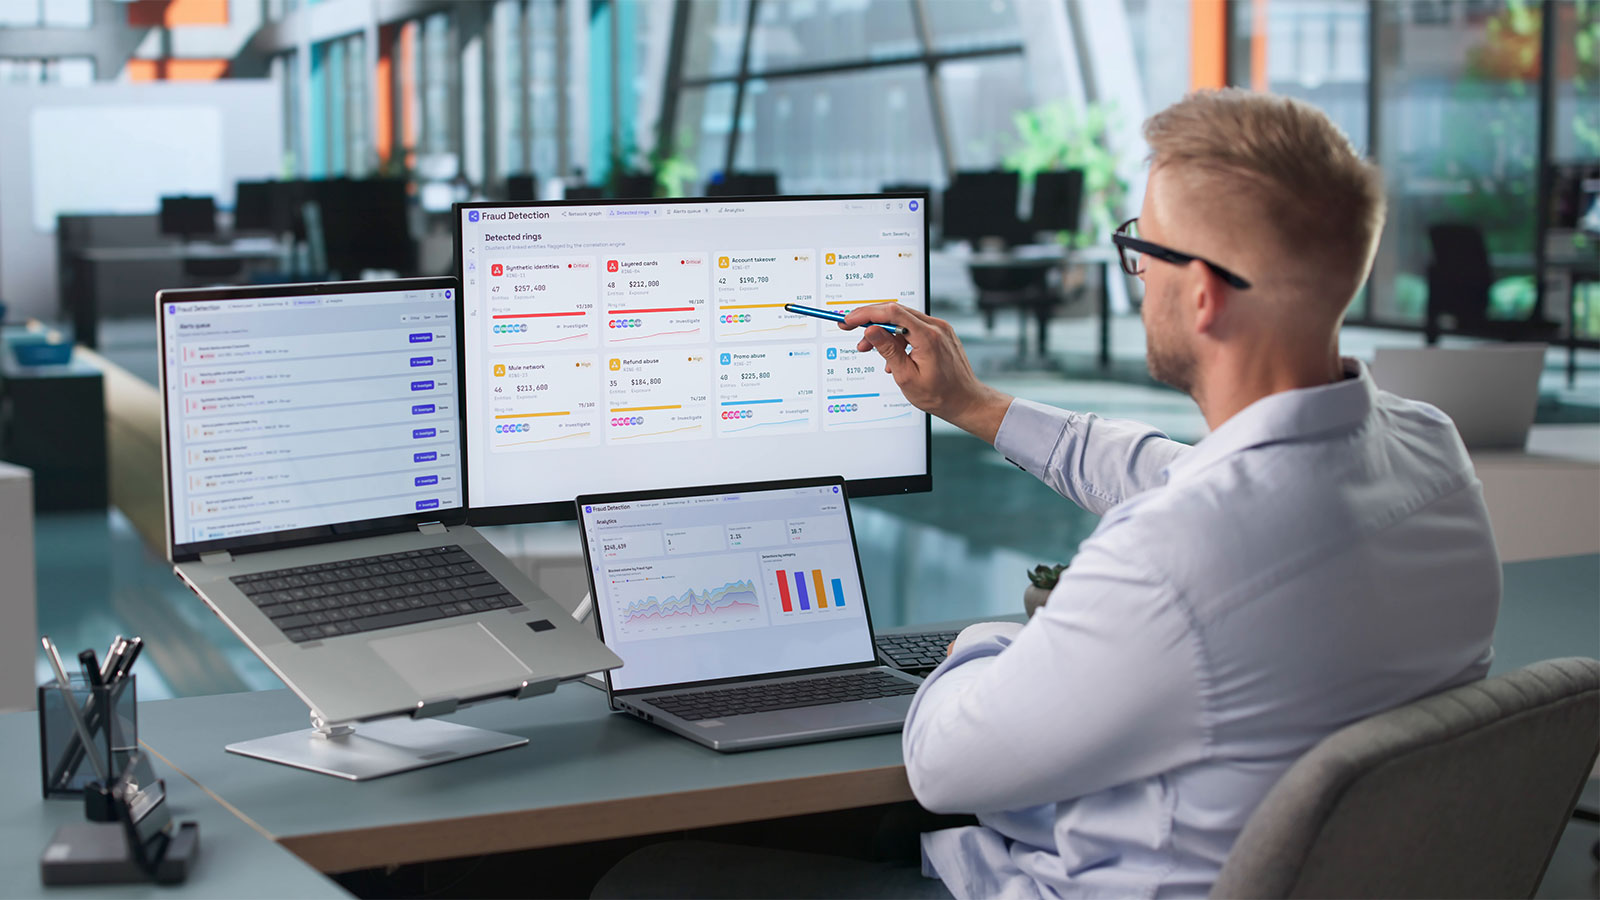
Tips and whistleblower hotlines remain the most common way occupational fraud is detected, and they continue to be an essential part of an effective fraud detection program. But organizations now have another powerful tool: the ability to analyze enormous volumes of transaction data for patterns, anomalies and red flags that would be difficult, and sometimes impossible, to spot through traditional review alone.
Finding Fraud Sooner Can Mean Losing Less
The value of that early detection can be significant. According to the Association of Certified Fraud Examiners’ 2026 Occupational Fraud Report to the Nations, fraud detected through more proactive methods tends to be uncovered sooner and result in lower losses.
The numbers tell the story. Fraud discovered through notification by law enforcement continued for a median of 24 months and resulted in a median loss of $890,000. Automated transactions and data monitoring, by comparison, detected fraud in a median of seven months, with a median loss of $90,000. Surveillance and monitoring reduced the median duration to six months and the median loss to $66,000.
Organizations shouldn’t replace hotlines, internal audits or experienced investigators with algorithms. Just as baseball teams learned to combine analytics with traditional scouting, organizations can use fraud analytics to make their existing detection and investigative efforts more focused.
Analytics helps answer a deceptively simple question: Where should we look?
That may be in a vendor category where costs are dramatically higher than those of comparable organizations. It may be a purchasing-card transaction that doesn’t match the employee’s expense report. Or it may be thousands of seemingly unrelated benefit claims that turn out to share a bank account.
The data doesn’t prove fraud. It identifies something worth investigating.
What Does Fraud Analytics Look Like in Practice?
Fraud analytics doesn’t have to begin with sophisticated artificial intelligence or an elaborate technology platform. Sometimes it starts with a simple question: Why are we paying so much more than everyone else?
Consider a school district paying for lawn maintenance. On its own, the district’s total spending might not appear unusual. But when internal auditors analyzed historical lawn-maintenance costs on a per-acre basis and compared them with those of other school districts, something stood out: the district was paying nearly three times as much as its peers.
The auditors dug deeper, reviewing invoices, emails and other records. They discovered payments to the lawn-maintenance vendor for services that had not been performed. Law enforcement subsequently identified evidence of possible cash payments between the vendor and a district executive.
That example captures the basic fraud analytics process: identify the anomaly, investigate the red flag and determine the root cause. The analysis may reveal a perfectly reasonable explanation, or it may point to something that warrants further investigation.
The same principle can be applied across very different kinds of data.
In another investigation, an employee used an organization’s purchasing card to make personal purchases. While the employee’s expense report described the purchases as three $100 thumb drives, the itemized transaction details provided by the bank (Level 3 data) indicated that the employee purchased three $100 Visa gift cards. That discrepancy prompted investigators to examine the employee’s other transactions. Ultimately, they identified more than $100,000 in unauthorized purchases over several years, supported by fabricated receipts and expense reports.
In neither case did the data prove fraud. It showed investigators that something didn’t make sense.
When the Volume of Data Changes the Problem
That ability becomes even more important when the volume of transactions makes conventional review impractical.
During the COVID pandemic, for example, the New York Department of Labor experienced an extraordinary increase in attempted unemployment-benefit fraud. Fraud attempts grew from 94 in 2019 to more than 400,000 in 2020 and more than 1 million in 2021. Spreadsheet-based analysis simply could not scale to meet the problem.
The department began using AI technology with fraud analytics to identify patterns and anomalies across large volumes of claims. Among the red flags: multiple claims filed under different addresses but connected to the same bank account, as well as non-resident profiles appearing in a state program. According to the presentation, the effort prevented more than $33 billion in attempted theft of benefits.
AI Raises the Stakes on Both Sides
Artificial intelligence is expanding the capabilities of fraudsters while also giving organizations new ways to detect them.
California community colleges offer a striking example. Since 2024, the colleges have lost more than $30 million to scammers posing as legitimate students to obtain financial aid. The problem accelerated with the growth of online classes and the availability of AI tools that can help scammers create fake student identities and applications. At some colleges, more than 30% of applications were identified as fraudulent.
Now colleges are fighting technology with technology. AI can help identify patterns consistent with fake students, such as applications originating from foreign IP addresses or a phone number associated with an applicant at another campus.
Other emerging applications go well beyond transaction analysis. AI-assisted tools can help detect deep-fakes and synthetic identities, cross-check information in documents, images and voice data and identify potentially fabricated receipts and invoices. They can also support continuous risk assessment and escalate significant risks for human review.
Human review remains essential. Fraud analytics is most useful when it helps investigators separate the transactions that deserve attention from the thousands or millions that probably don’t.
You Don’t Need to Start with Sophisticated Technology
Organizations don’t necessarily need an advanced technology platform to begin. Familiar tools such as Excel, Power BI and SQL can organize and test data, combine information from multiple sources and make patterns easier to see. Workflow automation tools can extend those capabilities when datasets become too large or numerous for conventional approaches.
A successful approach starts with the questions the organization is trying to answer.
Where are costs unusually high? Which transactions don’t fit the expected pattern? Are the same vendors, employees, bank accounts or addresses appearing in places they shouldn’t? Are hotline reports clustered in a particular office, geography or service line?
Analytics provides another way to ask those questions and to ask them across far more information than investigators could reasonably review one transaction at a time.
The Strongest Approach Uses Both
That brings us back to Moneyball.
Baseball’s analytics revolution didn’t ultimately prove that data was better than experienced scouts. It demonstrated that organizations could make better decisions when they combined information that could be measured with the judgment of people who understood what they were seeing.
Fraud detection is much the same.
Tips and hotlines remain the most common method of detecting occupational fraud. Internal audits, management review and experienced investigators remain essential. But analytics gives those traditional methods another source of information, helping identify anomalies, make connections and direct attention toward risks that otherwise might remain buried in the data.
And as AI and other technologies make sophisticated analysis increasingly accessible, organizations have more opportunities to move from investigating fraud after the damage has been done toward identifying warning signs earlier.
The goal isn’t to replace the investigator with the data. It’s to give the investigator a better idea of where to look.
How Weaver Can Help
Businesses can achieve stronger fraud detection outcomes by combining data analytics with the experience and judgment of skilled professionals. Weaver’s Forensics and Litigation Services team helps organizations detect issues earlier, strengthen oversight and enhance their ability to respond to evolving fraud threats.
Contact us to learn to learn more about using fraud analytics to strengthen monitoring and investigative efforts.
©2026
International Fraud Awareness Week Series
Identifying and addressing fraud and corruption helps organizations foster a fairer, more transparent and ethical workplace for everyone. This four-part series examines new technologies to help uncover traditional schemes, what increased fraud enforcement means for organizations and emerging health care risks facing fraud examiners. It also explores how artificial intelligence is equipping organizations with smarter tools to detect and prevent fraud.
- Part 2: Fraud Enforcement Intensifies: What Organizations Need to Know
- Part 3: What Today’s Health Care Risks Mean for Fraud Examiners
- Part 4: Same Fraud, Smarter Tools: How AI is Changing the Fraud Landscape
